Finance & Payroll
Fees in, payroll out, books that balance. Controls that survive an audit.
- Bursars
- Accountants
- Head teachers
- Boards
Books your auditor trusts. Approvals no one can fake.
Dr 1,200,000 · Cr 1,200,000
every posting, both sides
True general ledger
Reports are read from the books, not a spreadsheet beside them.
Termly · plan · credit note
each one a posting
Fees, plans and credit notes
Bill, discount or refund. The parent statement stays reconciled.
Income tax · pension · withholding
worked out from the rules your tax office sets
Payroll with statutory deductions
Payslips and the statutory returns come out of the same run.
Budget → requisition → payment
one ledger, one trail
Budgets, requisitions and vendors
Commitments and spend stay visible against the budget line.
What it looks like in Brim
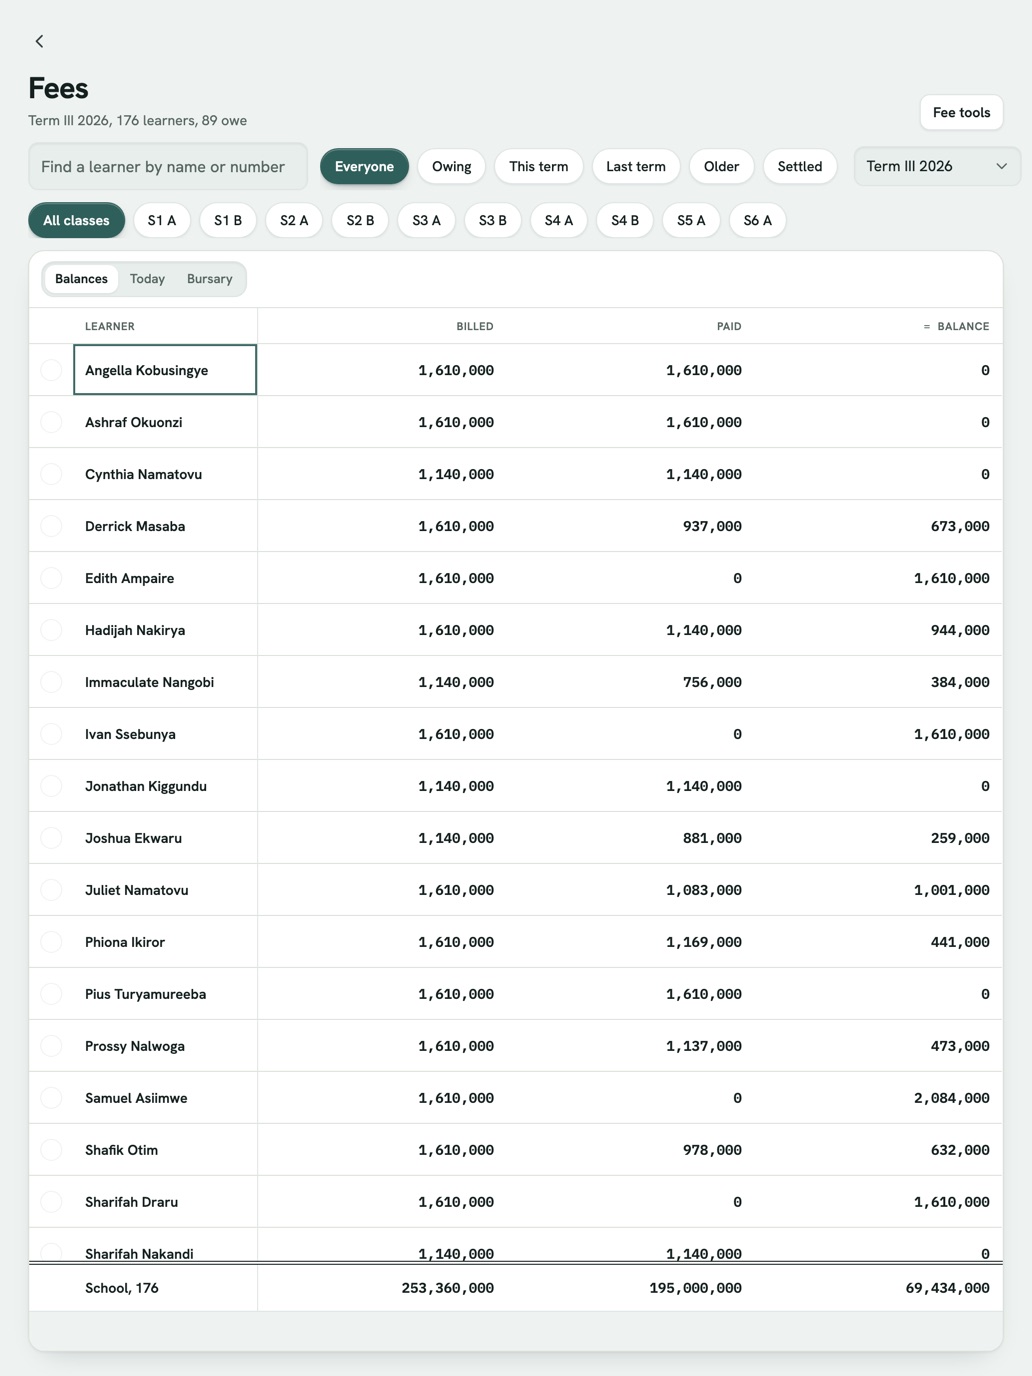
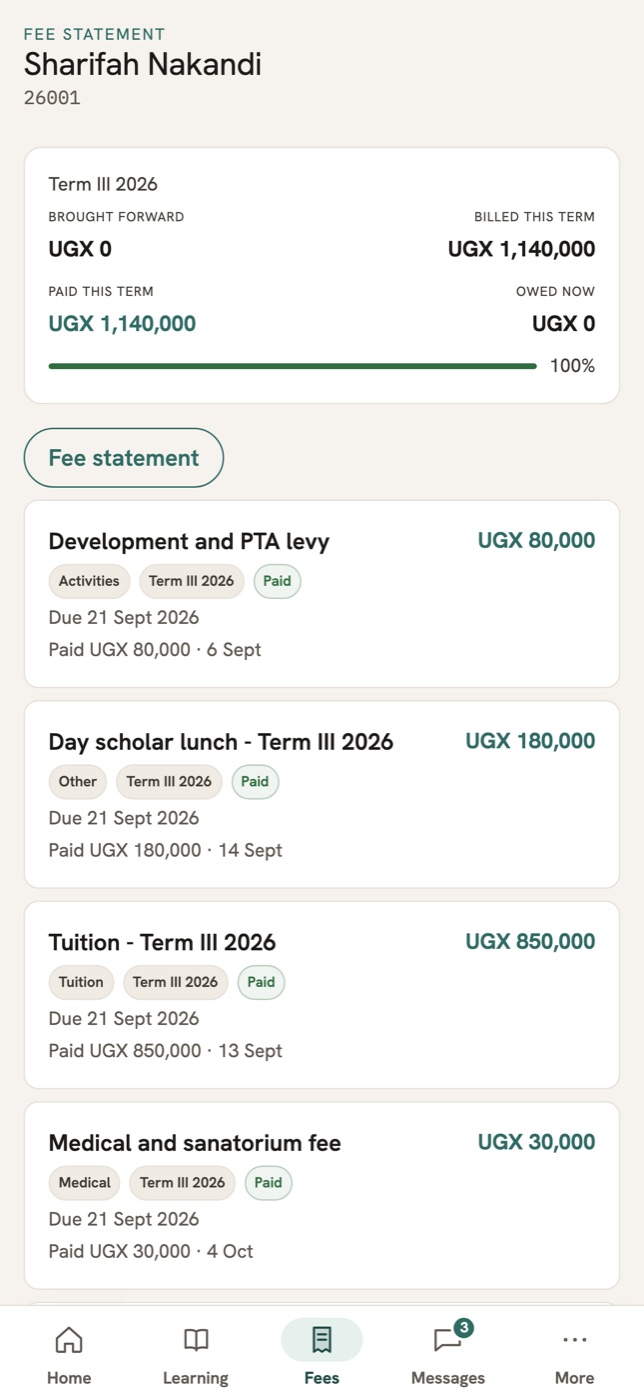
The fee registerBilled, paid and the balance for every learner, with the school total at the foot. The family’s statementEach charge and payment, with a receipt for every one. PAYE monthly bands
URA · resident · UGX0 – 235,000Tax free0%235,001 – 335,000of the amount over 235,00010%335,001 – 410,000+ 20,000 fixed20%410,001 ++ 25,000 fixed30%Income above 10,000,000/month carries an additional 10% on the excess. Payroll applies all of this from source.
PAYE, straight from the source.The monthly tax bands applied the way your tax office sets them, such as URA in Uganda. No hand-kept tax table to drift out of date.
Three steps, start to finish
- 1
Post
A fee, payment or salary is captured as a balanced double-entry journal. Never a side spreadsheet.
- 2
Check
A second authorised signer approves it. The hand that posts can never be the hand that approves.
- 3
Report
Trial balance, income statement and the tax and pension returns read straight from the ledger.
Maker-checker, enforced in the database.
Whoever posts a transaction cannot approve it. That rule lives in the database, beneath every screen, so the numbers you export are the numbers your auditor finds.
Controls that survive an export.
A. Nakato
posts the entry
B. Mukasa
approves it
A. Nakato cannot approve her own entry. That refusal comes from the database itself.
See the finance office in a walkthrough
See finance working on your own school's records. Brim brings your records in, trains your staff and supports your team every term.
Or write to brim@nacre.systems